A water damage claim can feel overwhelming when your home is wet and you are not sure who to call first. Here is how the process usually works in Ontario, step by step — and what you can do to keep it moving.
1. Stop the damage and keep everyone safe
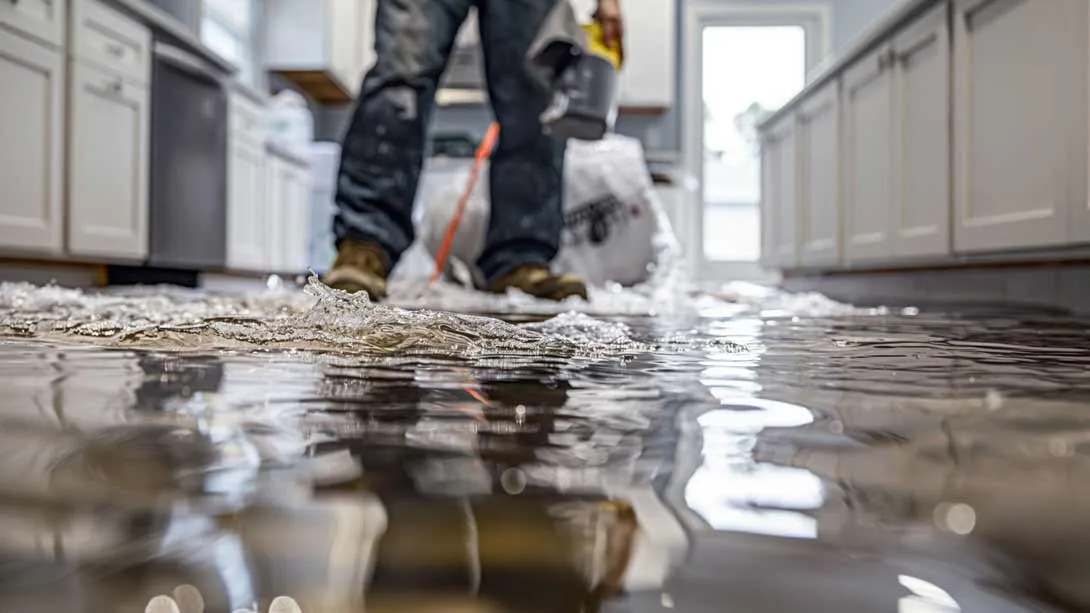
Shut off the water, turn off power to wet areas if it is safe, and start removing water. Most policies expect you to take reasonable steps to prevent further damage, and emergency mitigation is usually part of the claim.
2. Document everything before cleanup
Take photos and videos of the water source, the water level, damaged walls, floors and belongings. Keep damaged items until the adjuster says you can throw them out, and save receipts for anything you pay for, like fans or a hotel stay.
3. Call your insurer and open a claim
Report the loss as soon as possible — most insurers have a 24/7 claims line. You will get a claim number and an assigned adjuster. Ask what your policy covers and what your deductible is.
4. The adjuster reviews the damage
The adjuster visits or reviews photos to confirm the cause and extent of the damage. A restoration company can record moisture readings and prepare a detailed scope and estimate in Xactimate, the software most Canadian insurers work with.
5. Drying, repairs and contents
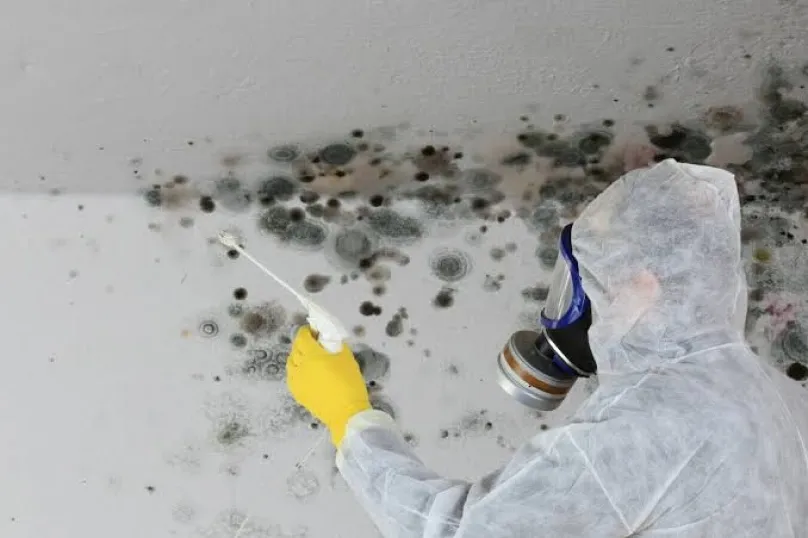
Once the scope is approved, the restoration team dries the property, removes damaged materials and rebuilds. Belongings are cleaned, packed out or listed as a loss. In most cases you can choose your own restoration company, even if the insurer suggests one.
6. Proof of loss and payment
Your insurer may ask you to sign a proof of loss — a formal statement of what was damaged and what it costs. Payment goes to you, the contractor or both, minus your deductible. Some policies pay full replacement cost only after the item is actually replaced.
What is usually covered — and what is not
Most Ontario home policies cover sudden and accidental water damage, like a burst pipe or a failed water heater. Sewer backup and overland flooding are usually optional coverage you have to add. Gradual leaks, long-term seepage and damage from poor maintenance are usually not covered. Every policy is different, so check yours or ask your broker.
Dealing with a water damage claim? Call us.
We document the damage the way adjusters need it, prepare insurance-ready estimates and can bill your insurer directly.
647-521-9250